Pricing a redevelopment bond on the strength of the surrounding neighborhood can miss the fragile part of its revenue: the growth above an established tax base. In the scenario below, most of the neighborhood's taxable value survives a downturn, while the income earmarked for improvements falls by half.
The distinction matters wherever future property-tax growth pays for today's streets, drainage or public spaces. Texas calls the designated area a tax increment reinvestment zone, or TIRZ. Its financing mechanism separates revenue attributable to the original property value from revenue attributable to subsequent growth.[1] A bond supported by that increment needs a forecast of the difference, not merely a reassuring valuation of the whole.
The base stays behind
Under the Texas framework, the starting point is the taxable value of real property when the zone is designated. With boundaries unchanged, that base remains the subtraction from later taxable value. Taxes attributable to the base continue to flow to the participating taxing units; the designated portion of taxes on the excess goes into the improvement fund.[1][3]
Participation is another filter. A city or county can dedicate only part of its increment. The property's combined tax bill therefore cannot simply be treated as project revenue: the calculation needs each participating authority's rate and committed share.[2]
Nor does a TIRZ designation itself impose a higher tax rate. The mechanism redirects a portion of collections. Higher property values can increase the underlying bill, but the financing arrangement and the taxpayer's liability are different questions.[5]
The same neighborhood, a smaller difference
Consider a hypothetical zone with an $80 million base and $100 million of projected current taxable value. Assume an effective dedicated rate of 1% on the excess: this combines the participating tax rates and their committed shares. Hold that rate, the zone's boundaries and participation terms constant, assume full collection, and exclude other revenues and fund expenses. These are modeling assumptions, not a quoted Texas tax rate or an actual bond forecast.
The resulting annual property-tax contribution is $200,000: subtract the base from current value, then apply the dedicated rate.
Now suppose taxable value comes in at $90 million. Repeating the same calculation produces $100,000. The neighborhood has lost only a tenth of its projected total value, but the fund has lost half its projected contribution. These results are arithmetic derived from the stated assumptions.
The base explains the amplification. It absorbs none of the decline; the entire reduction comes out of the smaller layer of value above it. A district with an increment already large relative to its base would be less sensitive to the same proportional decline in total value. A district only slightly above its base would be more sensitive.
This is a scenario for taxable values, not an assertion that a fall in advertised house prices immediately changes the fund's receipts. The Federal Highway Administration's TIF primer distinguishes assessed values from market values and notes that assessment data can lag market conditions.[4] The finance forecast must follow the tax roll and collection calendar.
Three outcomes after the revenue miss
The plan still works. If scheduled payments and other required uses fit within the lower receipts, the forecast loses headroom without developing a cash deficit. Less ambitious borrowing, accumulated cash or additional committed revenue can make the same property outcome manageable. The existence of sensitivity does not establish distress.
The developer waits. In the reimbursement arrangement described by the Texas Comptroller, a developer funds an improvement and receives repayment as money becomes available. A weaker increment can therefore extend the developer's funding period.[1] Whether unpaid amounts accrue interest, expire or have another payment source depends on the executed agreement. A completed pavement does not establish a fixed reimbursement date.
A scheduled debt payment needs support. A bond's due date does not automatically move when the tax roll disappoints. If available receipts and reserves are insufficient, the issue becomes the legally available sources of payment. Texas Tax Code Section 311.015 makes bonds issued under that section payable from the zone's tax increment fund and expressly says they are not general obligations of the issuing municipality.[3] The city's name alone does not promise access to its entire budget.
That statutory rule should not be stretched into a claim that every financing associated with a TIRZ has identical security. Read the actual instrument and its revenue pledges. The FHWA primer describes different TIF financing structures nationally, including arrangements with additional support.[4] The cash-flow calculation identifies exposure; the documents identify who bears it.
The strongest counterweight is a credible second source
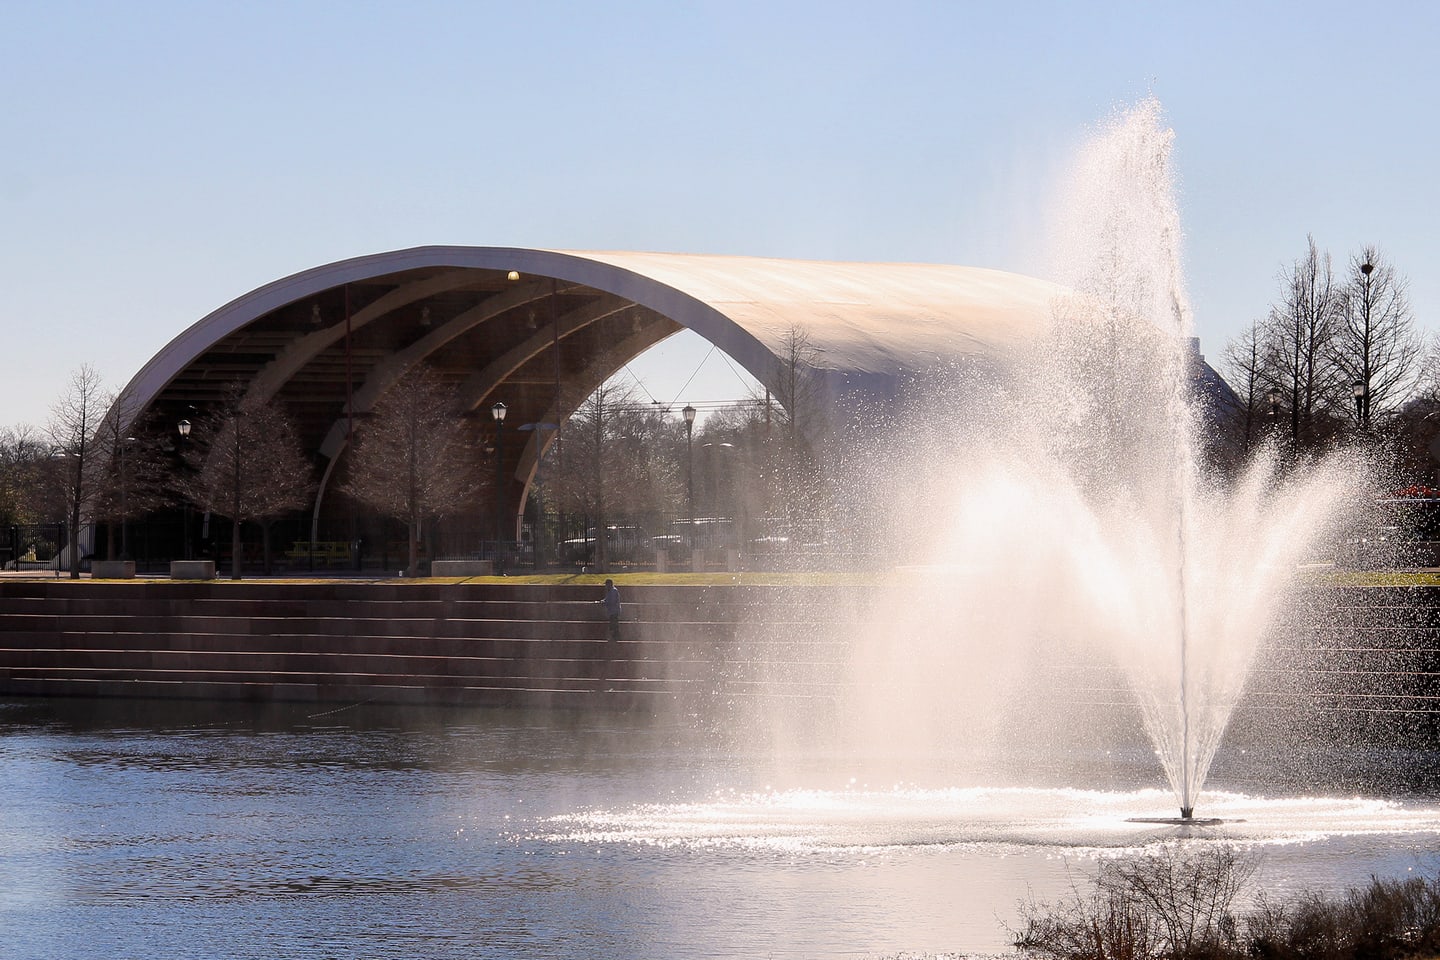
A growing increment can provide useful funding for infrastructure that makes development possible. Austin's Mueller project, photographed above, gives the mechanism a physical setting: a former municipal airport redeveloped into a neighborhood with homes, shops and public spaces.[5] The question is how conservatively a financing commits the future income.
The strongest answer to the downside case is an enforceable payment source that does not rely on the same property-growth forecast. The FHWA discusses contingent special assessments as one possible backstop where authorized, while distinguishing them from tax increments.[4] Such support transfers the burden; it does not make infrastructure free.
The payment-shortfall thesis is falsified for a particular financing if documented, available resources cover its scheduled obligations even under the lower-revenue scenario. A reserve that merely postpones an unresolved recurring deficit would soften the timing without settling the longer-term question. Equally, a project financed only as cash arrives may need to slow spending without putting any bond payment at risk.
The next documents that matter
- At the next certified appraisal roll: compare taxable value with the financing plan's forecast, separating completed taxable development from anticipated construction. The relevant measure is the value that actually enters the increment calculation.[2]
- At the next tax-rate adoption or participation amendment: recalculate the dedicated contribution. A fixed base value does not fix the tax rate or the share committed to the fund.[2]
- Before the next scheduled debt payment or developer reimbursement: reconcile cash received, permitted reserve use and enforceable support. Texas's remittance rules allow a lag tied to tax delinquency and invoicing, so an annual revenue estimate is not a bank balance on the payment date.[2]
Sources
- Texas Comptroller of Public Accounts, "What is a TIRZ?" — base value, allocation of property taxes, and developer reimbursement when funds become available.
- Texas Comptroller of Public Accounts, Chapter 311 Frequently Asked Questions — participating shares, financing-plan requirements, amendments and remittance timing.
- Texas Legislature, Tax Code Chapter 311 — Sections 311.012 and 311.015, captured taxable value, boundary adjustments and the payment security of statutory tax increment bonds.
- Federal Highway Administration, Tax Increment Financing: Primer — chapter 10 on contingent special assessments and the glossary on assessed values and bond structures.
- City of Austin Financial Services, "Tax Increment Reinvestment Zones" — allocation mechanism and Mueller redevelopment context.
- Larry D. Moore, "Mueller lake park and hangar 2014," February 4, 2014, Wikimedia Commons — original photograph and attribution.