A ship with a $5.4 million recycling bid can leave its owner with only $4.8 million after the final voyage and closing costs. The valuation gap in this worked example comes from treating a delivered sale price as cash already available where the vessel sits.
That distinction matters whenever scrap value is used to support an aging ship’s purchase price. The steel provides a possible exit, but the owner must still turn a particular vessel, in a particular location, into an acceptable delivery. The relevant figure is the net amount collectible at that exit—not simply the largest quotation multiplied by a ship-size number.
Buy the ship’s weight, not its carrying capacity
Deadweight is a measure of what a ship can carry at its applicable maximum draught. BIMCO’s definition includes cargo, fuel, water, provisions and other operating loads. It is not the weight of the hull waiting to be cut apart.[1]
Lightship weight describes the empty, service-ready vessel itself. The FAO’s stability manual distinguishes that weight from the vessel’s carrying capacity: together, they make up its loaded displacement. Although the manual concerns fishing vessels, the distinction explains why a cargo-capacity figure cannot stand in for the ship’s own weight.[2]
The sale contract then specifies the payable basis. BIMCO’s older DEMOLISHCON form calculates the purchase price from light displacement tonnage, or LDT, and an agreed price per long ton. It excludes permanent ballast and requires documentary verification. A number labelled simply “tons” is therefore insufficient: both the weight and quotation must use the same unit.[3]
Reconstruct the terminal cash
Assume a hypothetical vessel has 12,000 long tons of payable LDT, already reconciled to the agreed exclusions, and a buyer offers $450 per long ton for delivery at an eligible recycling destination. These are illustrative inputs, not a current market quotation or a valuation of the ship in the photograph.
The multiplication is straightforward:
Gross recycling consideration = 12,000 × $450 = $5.4 million.
Now assume $600,000 of incremental seller-borne costs to complete the sale. This is an invented combined allowance for delivery, preparation and closing, not an industry cost benchmark. Assume no separate payment for remaining fuel or equipment, no taxes, and no debt repayment in this asset-level calculation.
| Valuation component | Amount |
|---|---|
| Agreed consideration on delivery | $5.4 million |
| Incremental costs borne by the seller | −$600,000 |
| Net recycling proceeds | $4.8 million |
The cost allowance consumes part of the apparent protection without any fall in the buyer’s price. A purchase model using the gross figure has overstated the exit cash before making a single forecast about steel demand.
This is an immediate-exit calculation. If recycling lies years ahead, the model must forecast the future net proceeds and discount them back to the purchase date. Today’s quotation cannot quietly become a guaranteed terminal payment. Equally, costs already included elsewhere in the model must not be deducted again.
Delivery is part of the asset
DEMOLISHCON makes the distinction tangible. Its delivery clause puts pre-delivery expenses, local port disbursements and crew repatriation on the seller; it also describes delivery under the vessel’s own power. Those provisions illustrate how a sale price can coexist with a substantial final bill. They are terms of that older form, not universal terms for every recycling sale.[3]
Current preparation requirements also affect whether a delivery can happen. BIMCO’s RECYCLECON 2026 framework links hazardous-material inventories, an approved vessel-specific recycling plan, facility authorisation and readiness documentation. The sequence matters: the seller’s readiness certificate depends on receiving the approved plan and authorisation documents.[4]
The valuation implication is practical. A ship with incomplete documentation may need more preparation time before the assumed sale can close. The analyst must establish who bears the resulting costs under the actual agreement. Neither the existence of a requirement nor the label “recycling” supplies a standard deduction.
A distant high bid may be unavailable
For large EU-flagged seagoing vessels covered by the EU Ship Recycling Regulation, the destination must be on the European List of approved facilities. The Commission updates that list as facilities enter or leave it. A quotation from an ineligible yard cannot support the same realizable value as an eligible offer.[5]
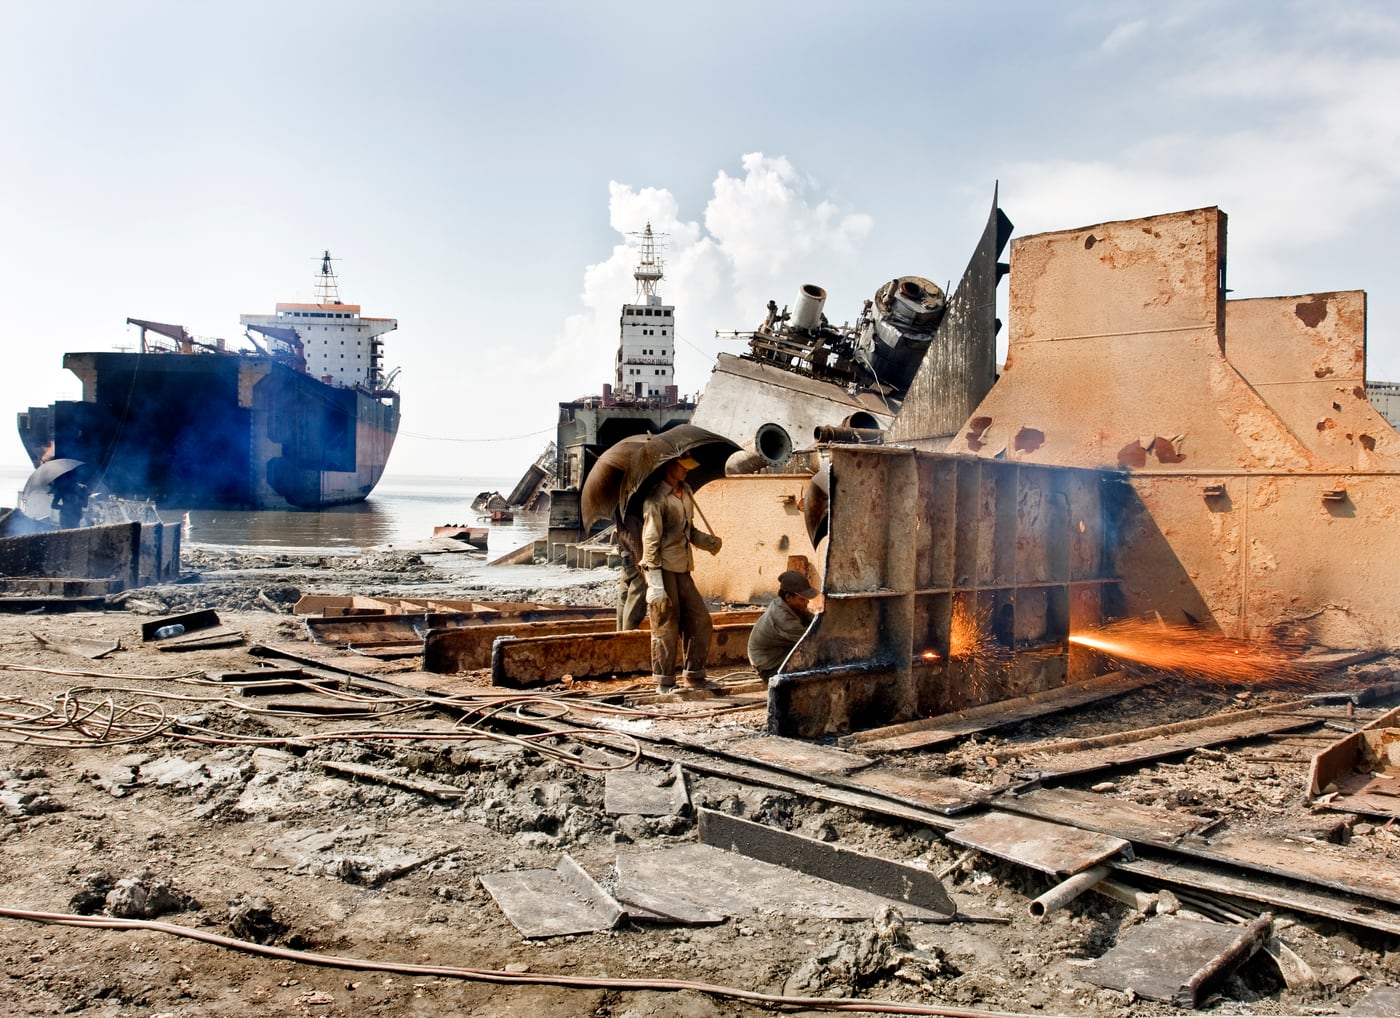
This is also why the photograph is dated explicitly. An archival image can reveal the scale and material texture of dismantling; it cannot establish that a facility is authorised to receive a particular ship today. Eligibility belongs in the valuation inputs alongside the vessel’s location and the buyer’s delivery terms.[4][5]
The strongest counterweight is a sale agreed on an as-is, where-is basis, with the buyer assuming the costs included in our allowance. If a credible buyer makes a binding, legally feasible offer near the gross figure on those terms, that is the falsifier for applying this example’s haircut. The seller’s net proceeds could be higher. Moving a cost to the buyer, however, does not guarantee that the buyer will leave the headline bid unchanged.
What would confirm the value
- When the bid becomes a contract: reconcile the payable LDT, its unit, included equipment and the delivery location. Replace indicative arithmetic with the agreement’s actual consideration.[3]
- Before the final departure: confirm the destination’s eligibility and the preparation documents, then update the seller’s remaining cost estimate against the voyage and completion plan.[4][5]
- On delivery and payment: reconcile the cash received with all incremental sale costs. That result tests whether the supposed scrap-value protection was available to the owner in practice.
Sources
- BIMCO SHIP PI, “META005 | DWT,” documentation version 4.0 — deadweight and the loads included in carrying capacity.
- Ari Gudmundsson, FAO, Safety practices related to small fishing vessel stability, 2009, printed page 4 — lightship weight, deadweight and displacement mass.
- BIMCO, DEMOLISHCON, 2004 sample, clauses 2, 8 and 12 — long-ton pricing, delivery-cost allocation and verification of payable LDT; an illustrative older contract form.
- BIMCO, “RECYCLECON 2026” — authorised facilities, hazardous-material inventories, approved recycling plans and the readiness-document sequence.
- European Commission, “Ships” — scope of EU ship-recycling rules and the regularly updated European List of approved facilities.
- Naquib Hossain, “Ship Breaking by Gas Cutting in Bhatiary Yard 01, Chittagong Bangladesh,” November 17, 2009, Wikimedia Commons — photograph and attribution, CC BY-SA 2.0.