A rising housing-consumption figure can look like fresh spending power, even when no extra money changes hands. Before treating it as a stronger consumer-demand signal, separate the price assigned to shelter from the cash available to its occupant: GDP includes rent that homeowners never pay.[1]
An accounting explainer ahead of the October 29, 2026 GDP and personal-income releases. The household figures below are hypothetical; they are not estimates of current US rents or growth.[6]
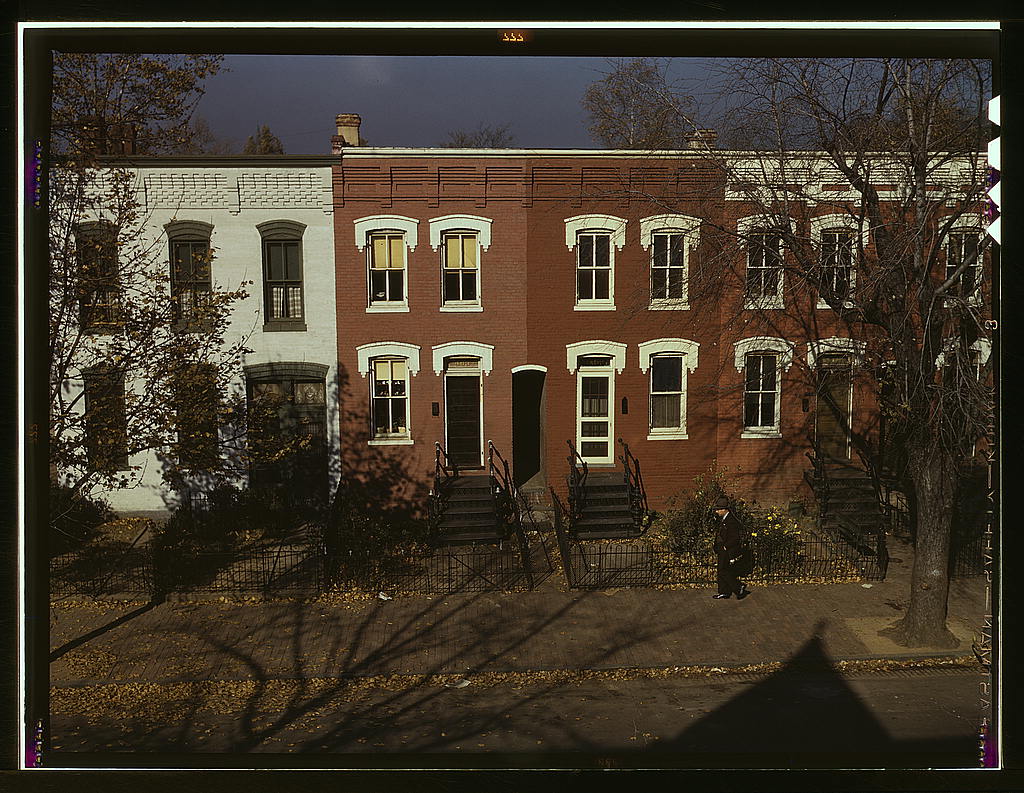
The house keeps working
Imagine comparable homes on the same street. A tenant pays $2,000 a month for one. The other is occupied by its owner. Both provide a place to cook, sleep and close the door against the weather. Counting only the tenant’s payment would make the second home’s service disappear from measured production simply because its occupant holds the deed.
BEA prevents that disappearance by estimating what the owner’s home would rent for. This is imputed rent. In our simplified example, each home supplies $24,000 a year of housing services. One payment reaches a landlord’s bank account; the other exists as a transaction in the national accounts.[1]
The house itself and its recurring service occupy different places in GDP. A newly built home enters investment. The shelter it subsequently provides enters consumption. Buying a durable asset and using its services are separate economic events.[1]
Paying off the loan changes another account
Now let the owner make the final mortgage payment. The bank’s claim disappears, but the rooms do not expand, the roof does not improve and the equivalent market rent need not change. The same shelter continues to be consumed.
Ireland’s Central Statistics Office explains the financing distinction clearly: mortgage principal repayments reduce a financial liability. Mortgage holders and otherwise comparable outright owners can have the same imputed rent while facing very different cash commitments. Applying that distinction to our example, eliminating the loan changes financing without automatically changing the housing service.[2]
There is nevertheless an income effect to track. BEA treats owner-occupiers as housing businesses for this calculation. It deducts expenses, including mortgage interest, maintenance, property taxes and depreciation, from imputed housing output to derive net rental income. Reducing interest expense can therefore raise the owner’s imputed net rental income even if gross housing consumption stays unchanged.[3]
That does not mean the full rent estimate becomes spendable cash. Nor should consumption and the associated income be added together as separate contributions to GDP: they describe different sides of production. The household’s bank statement remains necessary to understand its immediate spending capacity.
A higher sale valuation is different again. BEA’s rental-income measure excludes capital gains on existing assets. The owner may be wealthier, but an appraisal gain does not establish that the house produced more shelter this month.[3]
A larger dollar figure, the same rooms
Suppose the equivalent rent rises 5%, to $2,100 a month, while the home’s quality and service quantity remain unchanged. Annual imputed consumption becomes $25,200. The dollar value has risen, although the homeowner has written no additional rent cheque.
For this deliberately simple example, dividing the higher nominal value by the equally higher rental-price index leaves real housing consumption unchanged. The increase is a price movement. It would be a mistake to read it as either additional physical housing services or an equivalent increase in retailers’ prospective receipts.
BEA’s monthly method makes this distinction operational. Its real housing estimates reflect housing-unit stocks and quality; it uses rent indexes to turn those estimates into current-dollar values. For owner-occupied housing, the relevant price measure is the CPI for owners’ equivalent rent of primary residence.[4]
That CPI series measures rental-price change, not house-price appreciation. BLS collects price observations from rental units. It does not insert the latest selling price of the owner’s home into its shelter index. The distinction matters when a property boom and the rental market move at different speeds.[5]
An estimate anchored outside the household
Imputed does not mean invented without evidence. BEA’s annual estimates use American Community Survey rents and housing characteristics, including location, structure type, rooms and age. An additional owner premium addresses quality differences between owned and rented homes. Recent estimates must also bridge gaps before fuller survey data arrive.[4]
The strongest counterweight to dismissing this as statistical fiction is the service itself. An outright owner really does receive accommodation without paying a landlord. Removing that benefit from GDP would make comparisons depend on whether households happen to rent or own. The CSO emphasizes this international-comparability problem: a country should not look less productive merely because more residents own their homes.[2]
The measurement still answers a narrower question than a consumer-stock investor might have. More valuable shelter is economically meaningful; it does not show that households have placed more orders with shops or restaurants. Conversely, debt repayment can improve a household’s future cash position while leaving this particular consumption line unmoved.
My working interpretation of a consumption surprise concentrated in rising imputed-rent prices would therefore be limited evidence of stronger discretionary demand. The falsifier is a detailed release showing that the surprise instead comes from broader real purchases outside housing, supported by stronger cash income. That would require abandoning the rent-repricing explanation for the headline strength.
Three checks at the release desk
- October 29 GDP release: distinguish housing services within consumption from residential fixed investment. A stronger rental valuation and more construction answer different growth questions.[1][6]
- October 29 Personal Income and Outlays release: compare current-dollar housing consumption with its real measure, then inspect wages and real purchases outside housing. This tests whether a nominal rise is reaching household cash income and purchase volumes.[4][6]
- November 25 GDP and personal-income releases: revisit that interpretation with revised third-quarter estimates and October consumption data. Broadening real demand would overturn a reading based mainly on rent repricing; repeated nominal housing strength alone would not.[6]
Sources
- U.S. Bureau of Economic Analysis, “Why does GDP include imputations?” — rental equivalence, housing services and the distinction between new-home investment and consumption.
- Central Statistics Office, Ireland, “Imputed Rent” — ownership-neutral national accounts, mortgage principal and the difference between housing services and cash payments.
- BEA, “What is rental income of persons?” — gross housing services, deductible expenses, imputed net rental income and exclusion of capital gains.
- BEA, NIPA Handbook, Chapter 5, “Personal Consumption Expenditures,” updated December 2024, pages 5-45–5-47 — annual rental estimates, owner premium, monthly housing stocks and price adjustment.
- U.S. Bureau of Labor Statistics, “Measuring Price Change in the CPI: Rent and Rental Equivalence” — shelter services, rental observations and the treatment of house purchases.
- BEA, 2026 release schedule, checked October 29, 2026 — scheduled October 29 and November 25 GDP and Personal Income and Outlays releases.
- Library of Congress, Louise Rosskam, “Row houses, corner of N and Union Streets S.W., Washington, D.C.,” between 1941 and 1942, LC-USF35-629 — archival photograph on the Library’s official Flickr account.