An agreed $10 million business valuation can produce a $9.6 million purchase payment without anyone changing the earnings forecast or the valuation multiple. In this hypothetical acquisition, the missing value is operating working capital that the price assumed would arrive with the business.
A parts distributor makes the distinction tangible. Its buyer needs more than the trading name and customer relationships: there must be stock to dispatch, customer invoices to collect and a manageable pile of supplier bills. A working-capital target, often called a peg, specifies the agreed balance to be delivered at closing. Under a dollar-for-dollar adjustment, a shortfall reduces the price and an excess increases it.[1]
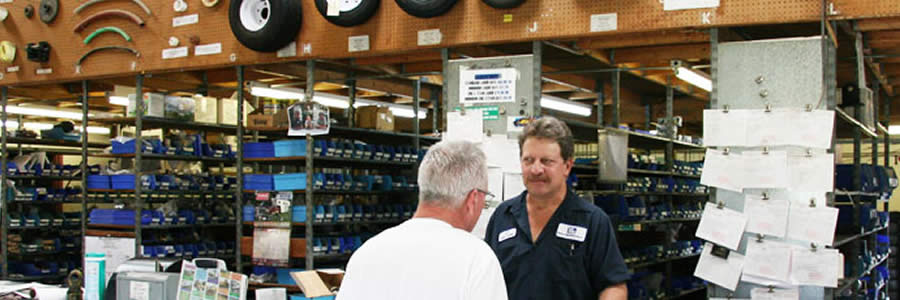
The price already assumes something on the shelves
Enterprise value is the agreed value of the operating business. The amount payable for its equity then depends on the purchase agreement's adjustments. A common structure adds cash, subtracts debt and seller transaction expenses, and adjusts for working capital above or below the agreed normal level. WilmerHale describes this bridge in its discussion of private-company acquisitions.[2]
The distinction prevents a basic valuation error: adding all the inventory and receivables to an enterprise value that already assumes normal operating working capital. The adjustment concerns the difference from the target, rather than the entire balance delivered.[1][2]
For our distributor, assume the contract defines operating working capital as eligible receivables and inventory, less trade payables and operating accruals. Cash and financing debt are dealt with separately. This is an illustrative definition, not a universal accounting rule. Whiteford's guidance stresses that the parties must identify the included accounts and align them with the other purchase-price adjustments.[3]
A warehouse can look reassuringly full while that calculation remains weak. Some stock may be obsolete; some customer invoices may be hard to collect. The contract's valuation policies determine what those balances contribute. Counting boxes answers a different question from establishing their agreed carrying value.[3]
Walk from business value to the seller's payment
Use a $2 million peg and assume the final closing calculation delivers only $1.6 million of eligible operating working capital. All figures here are invented. Assume no cash or debt transfers with the business, and no transaction-expense deduction, escrow, earnout or other adjustment, so the working-capital effect remains visible.
The calculation has two steps:
Working-capital adjustment = $1.6 million delivered − $2 million required = −$400,000.
Final equity purchase payment = $10 million enterprise value − $400,000 = $9.6 million.
There is no earnings multiple applied to the shortfall. Under the assumed contract, this is a balance-sheet adjustment made dollar for dollar. Nor has the enterprise value necessarily fallen: the buyer has received less operating capital than the agreed valuation assumed.[1]
Consider how that shortfall could arise. Suppose the distributor would otherwise deliver exactly the $2 million peg. Just before closing, the seller collects $400,000 of receivables at their full carrying value and distributes that cash to itself. Assume nothing else changes, including the peg, and that the contract permits the distribution. The business now delivers $1.6 million of working capital, so the purchase payment falls by the amount withdrawn. The seller receives $9.6 million through the sale and $400,000 beforehand: the collection has changed the route by which the money arrives, without creating extra value.
That arithmetic also explains the buyer's position. The lower payment compensates for an asset that will no longer turn into cash after the takeover. It does not establish that the business needs an immediate cash injection of exactly the same amount; payment dates and operating needs still matter.
The target needs the same ruler as the closing balance
The harder negotiation concerns what counts as normal. EisnerAmper describes a trailing twelve-month average of adjusted working capital as a common starting point, while emphasizing that the period is negotiable. Seasonality, growth and changes in the business can make a different reference period appropriate.[4]
Imagine the distributor approaching its busiest selling season. An annual average can conceal the stock build needed at that particular closing date. Equally, a target based on an unusually congested warehouse could make the buyer pay for an inefficient inventory habit. These are reasons to examine the operating cycle before agreeing the peg, rather than treating the historical average as self-justifying.
Measurement must also be consistent. If the target includes a receivable balance measured under one reserve policy, switching policies solely for the closing calculation can create an apparent shortfall. The purchase agreement needs to settle the applicable accounting practices. It also needs to prevent a liability from reducing working capital and being deducted again as debt.[3]
The strongest counterweight to our deduction is a real, lasting reduction in the distributor's operating-capital needs. Better supplier terms or a shorter replenishment cycle might support a lower target, provided the agreement reflects that change. If the parties substantiate and adopt a $1.6 million peg, the example's $400,000 deduction disappears. That would invalidate applying the original haircut to this deal. A seller's unsupported claim that it can run leaner would not.
Closing day may leave the amount unsettled
The bank transfer at completion can be provisional. PwC describes a process in which the seller supplies an estimated closing statement and a later statement establishes the final balances. Crucially, the later calculation still measures the business at closing. It is not simply a fresh valuation based on how trading has gone under the buyer.[5]
The implication is easy to miss: a buyer preparing the accounts after taking control is measuring an earlier handover. Records of inventory, receivables and liabilities at that boundary matter more than the appearance of the warehouse weeks later. The contract's preparation and objection deadlines determine when each side must make its case.[5]
Three events would confirm or break this valuation:
- Before signing the purchase agreement: reconcile the peg to the distributor's operating cycle and agree a worked schedule of included accounts. A substantiated lower requirement would change the deduction.[3][4]
- At the closing stock count and ledger cutoff: compare the eligible balances with the agreed target, including the effect of collections or distributions made before handover. This establishes whether the assumed shortfall exists.[1]
- When the final closing statement and any objection notice are due: reconcile the estimate to the closing-date evidence under the contract's rules. The resulting settlement determines whether the illustrated purchase payment survives review.[5]
Sources
- Gen Oraa, BDO, “Importance of Net Working Capital (NWC) in M&A,” February 15, 2019 — the peg and dollar-for-dollar purchase-price adjustments.
- Stephanie C. Evans, WilmerHale, “Purchase Price Adjustments in Financial Services M&A Transactions,” February 12, 2025 — introductory explanation of the enterprise-to-equity price bridge in private M&A.
- Frank S. Jones, Jr., Whiteford, “Net Working Capital & Purchase Price Adjustments In M&A Deals,” September 18, 2024 — account definitions, asset quality, accounting consistency and avoiding duplicate deductions.
- EisnerAmper, “Net Working Capital and Key Considerations for Buyers and Sellers Contemplating a Transaction” — negotiated reference periods, normalized operating needs and contractual adjustment boundaries.
- PwC, “Better negotiations of post-closing price adjustments” — estimated and final closing statements, the measurement date and the contractual review process.
- Kennco Manufacturing, “Farm Equipment Parts and Accessories” — company-published photograph of its parts warehouse.