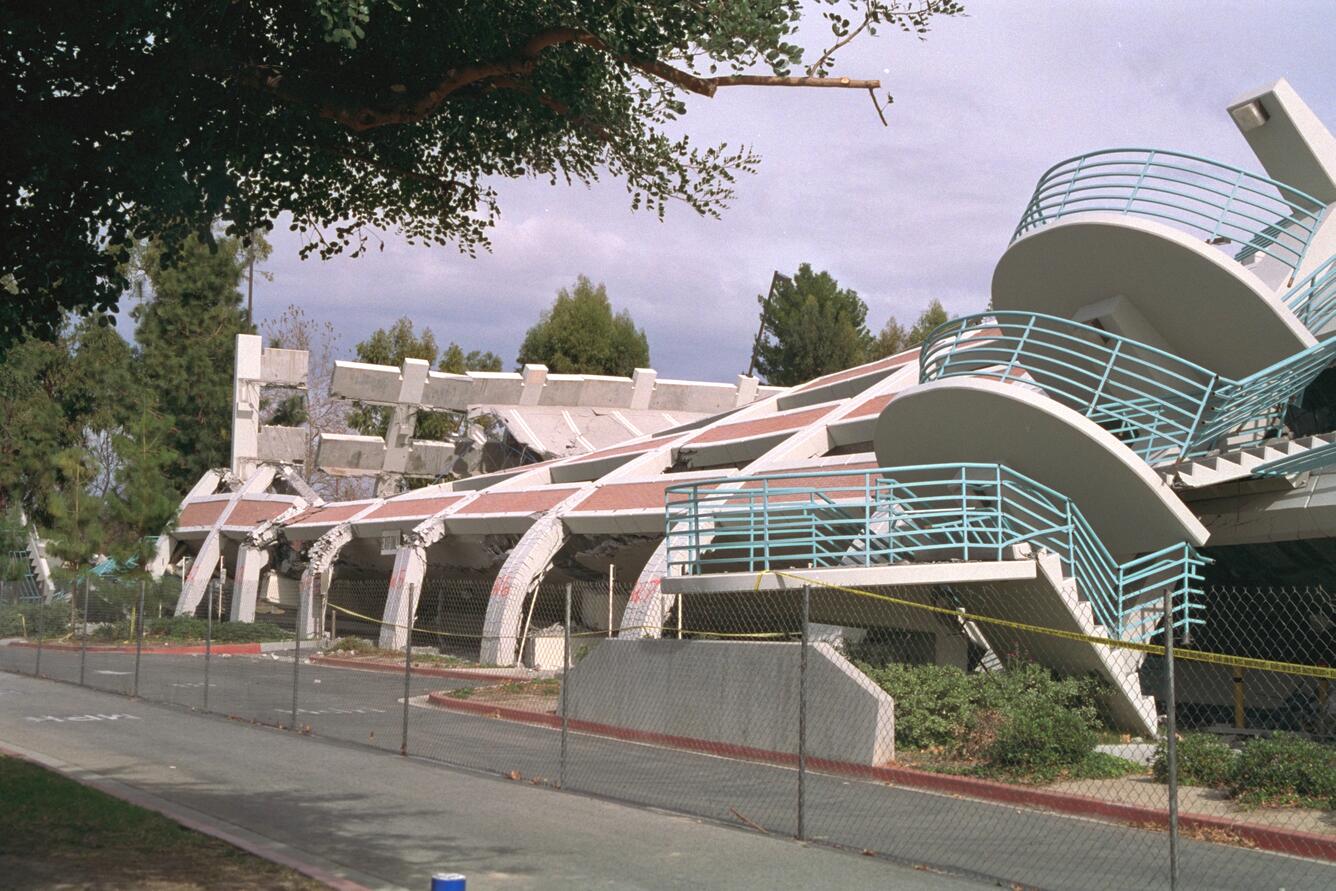
A fast-payout earthquake policy can leave a damaged business with no payout at all. The premium buys a defined trigger; the financing test is whether that trigger catches the cash shortfall the buyer needs to fund.[1]
Parametric insurance makes that distinction unusually visible. Instead of calculating the payment from an adjuster's assessment of damaged property, it links a pre-agreed amount to a specified event measurement. The National Association of Insurance Commissioners says the contract must identify the parameter, payment and independent verifier.[1] That can shorten the wait for money. It also makes the definition of the event part of the financial protection being purchased.
The same repair bill, three different funding outcomes
Consider a hypothetical business buying a policy that pays $250,000 when the designated data provider reports shaking at its insured location at or above an agreed threshold. Below that threshold, this simplified contract pays nothing. Assume it is in force, the premium has already been paid, the limit is unexhausted and all other conditions are satisfied.
After a quake, the business faces $300,000 in eligible emergency repairs and operating expenses, with $100,000 of unrestricted cash available. Assume those expenses also qualify as losses under this invented policy. Ignore tax and any other insurance recoveries during the emergency period. These are illustrative terms and amounts, not a quotation or a description of a particular insurer's product.
The trigger fires and money arrives before the bills. The payout covers most of the expenditure. The business uses $50,000 of its own cash to cover the balance and retains the rest of its reserve. Here, the policy performs the job management bought it for: it turns an external measurement into usable recovery funding.
The building is damaged but the trigger does not fire. The expense bill remains unchanged. With only its cash reserve available, the business must find $200,000 elsewhere or defer spending. The insurer has not necessarily disputed the damage or breached the contract. The agreed payment condition simply was not met.
The trigger fires, but the bills come first. The eventual insurance recovery is the same as in the first branch. Until it arrives, however, the business faces the same immediate funding gap as in the second. A promised payment and a bank balance available today have different uses when a contractor requires a deposit.
These branches separate two questions that a coverage limit cannot answer: will the contract pay for this event, and will the money arrive before the business runs short?
Why the shaking number can miss the loss
The USGS distinguishes earthquake magnitude, which describes the earthquake at its source, from intensity, which describes shaking at a particular place.[2] A headline magnitude therefore cannot establish what every insured location experienced. A location-based intensity trigger brings the measurement closer to the exposure, but it still measures something different from a business's complete financial loss.
This is the reasoning behind using a warehouse's own shaking conditions rather than treating every building in a broad region alike. It does not make the warehouse's construction, contents or dependence on interrupted services irrelevant. In our scenario, the threshold can remain unmet while the business still faces a repair bill.
The mismatch between payout and actual loss is called basis risk. It can run in either direction. In its evaluation of the Philippines' parametric catastrophe-insurance pilot, the World Bank describes a typhoon payout larger than the damage in the province that triggered it. Deciding how to allocate the money then caused delays.[4] That episode is not an earthquake claim; it demonstrates the wider problem of making an index-based payment serve needs that follow a different geography.
Commercial products can also have more conditions than the phrase automatic payout suggests. Swiss Re's QUAKE product uses USGS ShakeMap ground-shaking information at insured locations and describes a requirement for an officer-signed confirmation of the total loss amount.[3] That is a specific product's process, not a universal rule. A buyer still needs to distinguish the trigger calculation from the documentation required to release funds.
The strongest case for paying the premium
A mismatch does not make parametric cover useless. Rapid funding can matter even when it covers only part of the loss. Paying for temporary premises or urgent repairs may let a business restart while the larger reconstruction bill remains unresolved.
There is practical evidence of speed at sovereign scale. In its April 2022 account of the Caribbean Catastrophe Risk Insurance Facility, the World Bank reported payouts made within 14 days of disasters and described their role in financing initial response and maintaining government functions.[5] That record is not a settlement promise for the hypothetical business. It shows why buyers may reasonably value a product that trades detailed loss adjustment for a pre-agreed calculation.
The inference for our business is conditional: the policy is useful as a recovery-funding layer when plausible damaging events activate it and cash or committed credit covers the wait. The example establishes no fair premium. Pricing the purchase would also require the probabilities of those branches, expected payments and the cost of alternative funding.
What would make the funding case fail
The proposed role for this policy is to prevent an emergency cash shortfall. A scenario test showing a plausible quake that exhausts available cash while missing the trigger would invalidate treating this policy and reserve as an adequate funding plan. The contract could remain useful, but the plan would need another source of money.
Three events would test that assessment:
- At the next renewal quote: run damaging scenarios through the proposed trigger and payout schedule, including cases just below the threshold. Compare the unfunded bills with available cash and committed credit, not just with the advertised limit.
- When the designated post-quake dataset is released: check the insured locations, measurement and contractually specified data version. The provider's reading is relevant to entitlement; photographs of damage answer a different question.[1][2][3]
- At the contractual settlement deadline: reconcile the calculated payout, required documents and actual receipt against the repair and payroll calendar. Funding has to reach the spending decision to deliver its intended benefit.[3][4]
Sources
- National Association of Insurance Commissioners, “Parametric Disaster Insurance,” updated December 21, 2023 — event-based payments, contract parameters, independent verification and settlement speed.
- U.S. Geological Survey, “What is the difference between earthquake magnitude and earthquake intensity?” — source magnitude and location-dependent shaking intensity.
- Swiss Re Corporate Solutions, “QUAKE: Parametric insurance to close the earthquake protection gap” — location-based ShakeMap triggers and the product's loss-confirmation process.
- Benedikt Lukas Signer and Richard Poulter, “Disaster risk insurance: 5 insights from the Philippines,” World Bank — basis risk and the importance of payout-allocation rules.
- World Bank, “Risk insurance builds climate and disaster resilience in Central America and the Caribbean,” April 21, 2022 — CCRIF payout timing and initial-response financing.
- U.S. Geological Survey, “Northridge, CA Earthquake Damage” — archival photograph from the collection documenting damage after the January 17, 1994 earthquake.