A competitive foreign-exchange quote can still leave a treasurer exposed to losing the entire payment. June's BIS review brings that gap into focus: 90% of surveyed settlement used some form of risk mitigation, while 36% used payment-versus-payment, the mechanism that eliminates principal risk.[1]
As of September 24, 2026. Survey figures describe average daily settlement in April 2025; the examples below explain mechanisms rather than forecast losses.
The deal is agreed. The money is still travelling.
A wholesale currency trade changes balances in bank accounts. Each party instructs a bank to deliver the currency it owes, potentially through a different national payment system. Agreeing the exchange rate does not, by itself, coordinate those deliveries.[2]
Herstatt supplied the enduring lesson. When German regulators closed the bank in June 1974, counterparties had already paid Deutsche marks, but the dollars they expected in New York were withheld. The exposure reached the payment's full value. It was far larger than the cost of replacing a trade after a small exchange-rate move.[2]
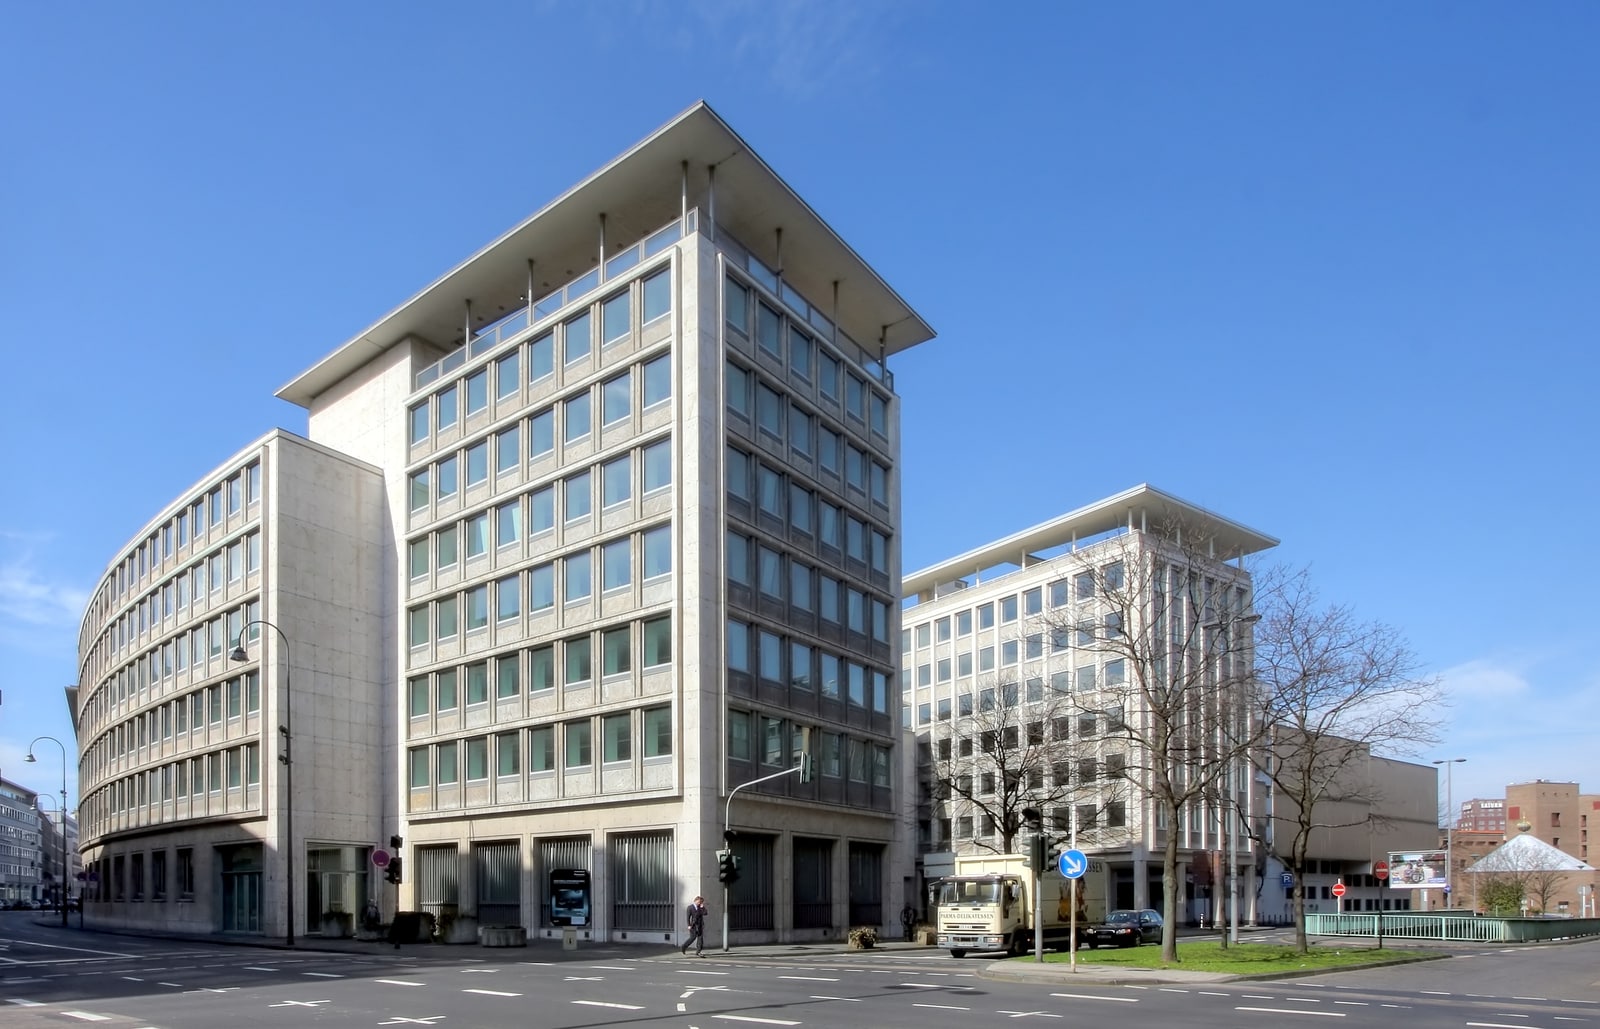
The photograph shows the bank's former Cologne premises decades later.[7] The building makes an otherwise abstract failure tangible: an ordinary banking business sat at one end of obligations that crossed currencies, institutions and business hours. The dangerous interval opened when a payment could no longer be recalled and the purchased currency had yet to arrive.[3]
What sits inside the reassuring percentage
The BIS divides April's settlement into distinct buckets. Beyond the share using payment-versus-payment, 54% used methods including pre-settlement netting, intragroup settlement or bank-account timing controls. These reduce exposure without eliminating it. The remaining 10%, more than $1.4 trillion daily, settled gross bilaterally, with the full payment exposed.[1]
These are settlement amounts, not expected losses. Mitigation methods offer different protections, and changed methodology prevents direct comparison with the 2019 and 2022 surveys.[1]
For a treasurer comparing bank services, that makes the settlement method part of the economic bargain. A narrow dealing spread is easy to compare. The operational terms determine what happens to the much larger sum being exchanged.
A smaller bill still has to be paid
Payment netting reduces the amount that needs to move. Where counterparties have eligible, offsetting obligations in the same currency, they can calculate a residual payment instead of exchanging every gross amount. That can save funding and reduce operational work.[4]
CLSNet provides a useful concrete example. It matches instructions and calculates bilateral net payment amounts at agreed cutoffs. Participants then arrange the actual payments outside CLSNet, through their correspondent banking relationships. The calculation service does not itself make the currency deliveries conditional on each other.[4]
Imagine the treasurer sees a much smaller outgoing payment after netting. That is a real improvement: less cash has to leave the account. But the remaining amount still needs a settlement arrangement. A successful reconciliation answers how much to pay; the subsequent transfer determines whether the counter-currency arrives. A provider's name alone cannot answer both questions.
CLSSettlement performs a different function. It uses payment-versus-payment, or PvP, to link the currency transfers, while multilateral netting also reduces funding needs. These protections can work together. Netting changes the funding requirement; PvP makes final delivery of one currency conditional on final delivery of the other.[5]
Protection can mean the trade does not settle
Consider an importer whose bank has arranged to buy foreign currency for a supplier payment. Under a basic PvP arrangement, if the counterparty fails to fund its side, the bank avoids paying away its currency without receiving the other. Yet the supplier still expects payment. Preserving the original funds does not put the required foreign currency into the importer's account.[3]
The Basel Committee distinguishes the remaining problems: obtaining replacement currency creates liquidity risk, and an adverse move in the exchange rate creates replacement-cost risk. PvP protects against the principal-loss mechanism; it does not promise that a failed counterparty's trade will complete.[3]
This is the strongest counterweight to a simple demand for universal PvP. Treasury teams still need workable funding arrangements and fallback procedures. The FX Global Code therefore sets a hierarchy: use methods that eliminate settlement risk where practicable; where that is unavailable, reduce the amount and duration of exposure and manage what remains. It also calls for counterparties to establish their settlement methods in advance.[6]
My reading is that treasury procurement should assess the dealing quote, the payment mechanism and the contingency funding together. The falsifier at a particular firm is evidence of full, enforceable PvP coverage for its relevant payments, including intermediary steps. That would remove the principal-risk gap described here, while leaving the separate delivery and liquidity questions.[3]
What to watch next
- At the September 30 treasury close: reconcile the actual settlement routes used against the methods agreed with counterparties. A trade routed outside the expected protection deserves an explanation.[6]
- When the next GFXC settlement survey is published: compare the method-level breakdown with a compatible reporting sample. The new collection follows April and October reporting windows; watch PvP coverage separately from the wider mitigation total.[1]
- At the next bank-service renewal or new-currency onboarding: ask how net amounts are delivered, when a payment becomes irrevocable, and how a missed incoming currency would be replaced. The answers determine whether a cheaper quote also buys an acceptable payment process.[3][4][6]
Sources
- BIS, “Uncovering FX settlement risk: new measures from the 2025 BIS Triennial Survey,” Quarterly Review, June 2026 — April 2025 settlement categories, amounts, methodology and survey follow-up.
- Federal Reserve Bank of New York, “Managing Foreign Exchange Risk” — settlement mechanics and chronology of the Herstatt failure; accessed September 24, 2026.
- Basel Committee on Banking Supervision, “Foreign exchange risks,” Basel Consolidated Guidelines, RMA20, January 1, 2026 — principal, liquidity and replacement-cost risks; indirect participation.
- CLS, “CLSNet,” February 2024, especially “How it works” — matching, bilateral netting and payment delivery outside the service.
- CLS, “CLSSettlement” — payment-versus-payment and multilateral funding netting; accessed September 24, 2026.
- Global Foreign Exchange Committee, FX Global Code, December 2024 edition, Principles 35 and 50 — settlement-risk hierarchy and agreeing settlement methods in advance.
- Raimond Spekking, “Ehemalige Gebäude der Herstatt-Bank (4975-77),” March 2010, Wikimedia Commons — source photograph, CC BY-SA 4.0.